Paying a loan before its scheduled end can save interest, but the last page of the settlement statement sometimes carries a surprise: a foreclosure or prepayment fee. In India, the answer in 2026 depends principally on whether the loan is fixed or floating, why it was borrowed, and when it was sanctioned or renewed. The Reserve Bank of India (RBI) has rules, but a blanket claim that every loan now has zero foreclosure charges is wrong.
The central rule for an individual using a floating-rate loan for a non-business purpose is that RBI-regulated lenders covered by its directions must not levy prepayment charges. The expanded framework applies to loans sanctioned or renewed on or after 1 January 2026. Older loans have their own applicable protections, and fixed-rate or business-purpose loans need separate checks. This guide explains how to identify your situation before making a repayment.
What the 2026 RBI rule actually covers
The RBI issued dedicated Pre-payment Charges on Loans Directions in July 2025, with the January 2026 start date, and subsequently consolidated conduct requirements into lender-specific Responsible Business Conduct directions. The rules are relevant across covered regulated lenders, including banks and certain non-bank lenders, but an institution’s particular regulatory category matters for business borrowing. They concern charges for pre-paying a loan—not normal interest accrued up to the repayment date, an outstanding instalment or unrelated contractual fees.
For a floating-rate loan to an individual for personal, family or other non-business use, the 2026 directions prohibit the lender from taking a foreclosure or part-prepayment fee. This is not limited to one source of funds: using savings, a bonus or proceeds from another legitimate financing arrangement does not by itself create a permissible charge. The directions also bar using a minimum lock-in period to defeat the prohibition for the covered category.
A floating-rate home loan is the obvious example, but the rule is framed around the loan’s purpose and rate rather than the marketing name alone. A floating-rate loan against property used for a non-business purpose can therefore need a different answer from a fixed-rate business loan against the same property. Confirm the classification with the lender and your sanction documents.
The decision table: rate, purpose and sanction date
| Question about your loan | What it means for prepayment |
|---|---|
| Individual + floating rate + non-business purpose, sanctioned or renewed from 1 Jan 2026 | The RBI’s no-prepayment-charge rule generally applies to covered regulated lenders. |
| Individual + fixed rate | Do not presume the fee is prohibited. Review the specific contract and disclosed lender policy. |
| Hybrid or special rate | Check whether the loan is on its floating phase when you prepay. |
| Business-purpose borrowing | There are additional rules for defined borrower groups and lender categories; do not apply the personal-use rule automatically. |
| Loan sanctioned before 2026 and not renewed | Previous floating-rate protections may apply. Identify the lender type and exact date rather than assuming the new directions retrospectively cover every condition. |
The date distinction is important: sanctioned or renewed on or after 1 January 2026 is not the same as merely having an EMI due in 2026. If a loan was booked in 2024 and is still running, ask the lender to point to the applicable earlier rule and contract clause. Some categories of older floating-rate loans already had prepayment protection, but the details differ by institution and purpose.
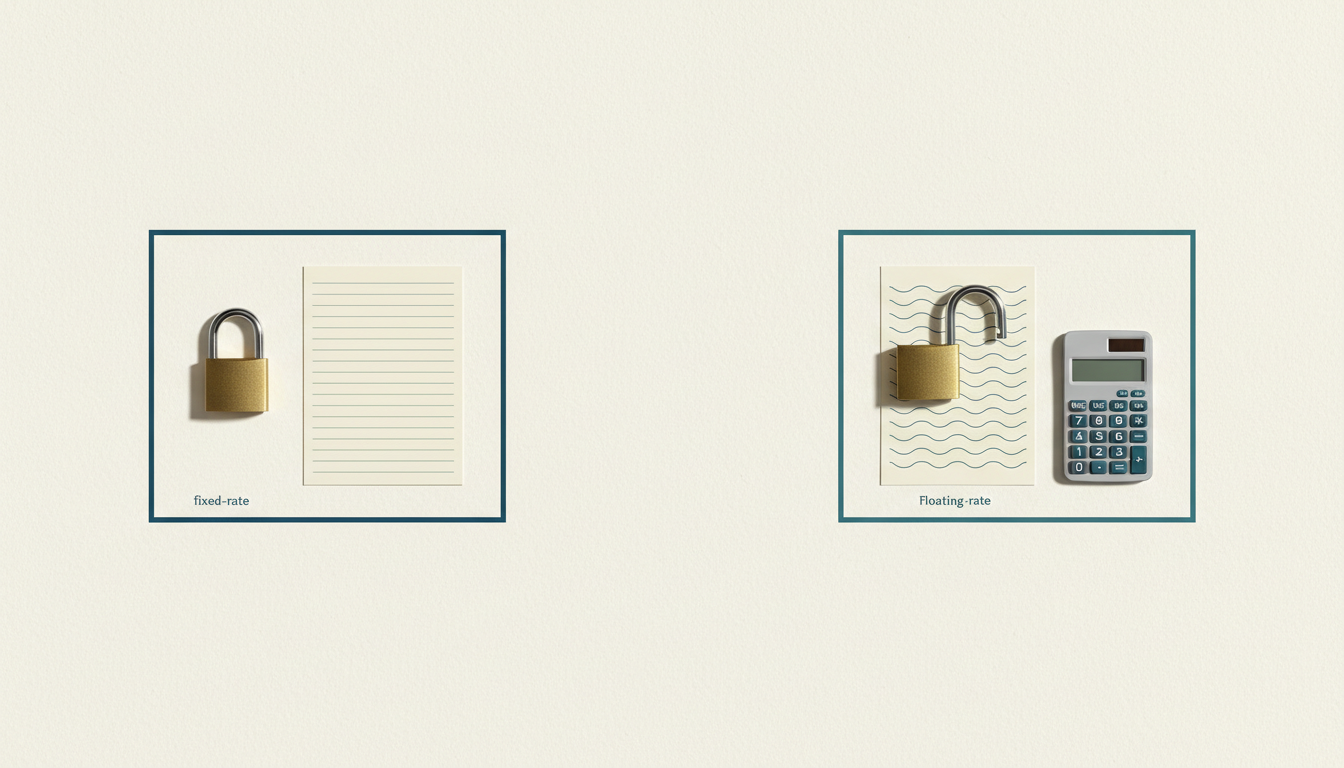
Why a fixed-rate personal loan may still carry a fee
Many retail borrowers use ‘personal loan’ to mean an unsecured, fixed-rate instalment loan. A fixed rate does not float with a benchmark, so the floating-rate prohibition cannot simply be copied across. Lenders may have a disclosed foreclosure fee where regulation and the loan terms permit it. Check the percentage, the base on which it is computed, applicable taxes and whether a minimum number of EMIs must be paid.
Do not confuse foreclosure with part-prepayment. Some contracts distinguish closing the entire balance from making an additional payment. Where a fee is allowed, the lender’s charges may vary by stage of the loan. The written sanction letter, agreement and Key Facts Statement (KFS) are more reliable than a sales conversation or an old product webpage.
How much interest might you save? A worked example
Consider an outstanding floating-rate balance of ₹10,00,000 at an illustrative 9% annual rate. If the loan charges interest monthly on the reducing balance and you pay an additional ₹1,00,000 before the next interest calculation, the immediate one-month interest reduction is approximately ₹750 (₹1,00,000 × 9% ÷ 12). This is a teaching example, not a bank quote.
The total saving is not ₹750 multiplied by every remaining month. It depends on the remaining tenure, future rate resets, the lender’s daily or monthly interest method and whether the extra payment reduces EMI or shortens tenure. Ask for two amortisation schedules—one without and one with the payment—and compare the total future interest, the revised final date and any permitted charges. You can also compare the offer with our guide to loan APR and the KFS.
The six checks before you send money
- Find the sanction or renewal date. Record both if the facility has been renewed.
- Confirm whether the outstanding rate is floating, fixed or hybrid today; use the latest rate-reset notice and contract.
- Identify the loan purpose and whether you borrowed as an individual, a business or another entity.
- Read the sanction letter, loan agreement and KFS for the exact prepayment/foreclosure entry and disclosed calculation method.
- Ask the lender for a dated foreclosure statement: outstanding principal, accrued interest, any eligible fees, tax and the quote’s validity date.
- After payment, secure the closure confirmation and release of security documents where applicable; check the final account status and credit-report update.
If you intend only a partial repayment, obtain written confirmation of whether the EMI falls or the tenor shortens. A shorter tenor generally reduces total interest faster when the EMI is maintained, although the right choice also depends on cash-flow needs. Retain a realistic emergency buffer; repaying every rupee of savings may cause a more expensive borrowing need next month.
What to do when the lender quotes a questionable charge
First ask the branch or customer-care team to specify the rule or contract provision and provide a line-by-line statement. Identify the lender type, sanction date, rate basis, borrowing purpose and amount being prepaid. A complaint saying only ‘RBI banned all foreclosure fees’ is too broad; a precise complaint is harder to dismiss with a generic reply.
If the explanation does not resolve the issue, send a documented grievance through the lender’s official complaint channel and preserve the reference number. Where the lender falls under the RBI Integrated Ombudsman Scheme and the conditions for escalation are met, use the RBI’s official Complaint Management System. Our RBI Ombudsman explainer sets out the response and filing windows. The Ombudsman is not a shortcut around the first complaint stage.
Mistakes that make a good prepayment decision costly
- Assuming all personal loans are floating. Many are fixed; check your actual rate type.
- Applying a 2026 rule to every old loan. The sanction/renewal timeline matters.
- Comparing only the fee percentage. Compare actual rupees of fees, interest saved and the term remaining.
- Ignoring the quote validity date. Daily accrued interest may change the closure figure.
- Leaving no proof. Save the payment receipt, final statement and no-dues confirmation.
Sources and scope
The rule summary is based on the RBI Commercial Banks Responsible Business Conduct Directions, consolidated text, the July 2025 prepayment direction preserved as an archive, and the RBI’s official FAQ on floating-rate EMI reset choices. The archived July direction should not be mistaken for the sole current consolidated rulebook. The exact current direction for your lender type and the loan documents govern a specific case. This is general reporting, not personalised financial or legal advice.
Frequently asked questions
Does the 2026 rule remove fees from every personal loan?
No. The strongest blanket protection concerns covered floating-rate, non-business loans to individuals. Fixed-rate contracts and business-purpose borrowing need their own regulatory and agreement checks.
Can my lender charge because I use another bank’s money to close the loan?
For a covered floating-rate individual non-business loan, the source of funds should not be used to impose a prepayment charge prohibited by the directions. Separate legitimate interest or administrative items must still be distinguished on the statement.
Is a part-payment treated differently from full foreclosure?
The covered prohibition applies to relevant prepayments in part or in full. Where charges are otherwise permissible, read the agreement’s separate entries for each type of payment.
Will the bank automatically reduce my EMI after prepayment?
Not necessarily. The loan terms and selected instruction may reduce EMI, tenor or both. Ask for a revised repayment schedule and confirm your choice in writing.
Last checked for this guide: 31 October 2026. RBI regulatory directions can be amended; verify the current version and your lender’s written statement before acting.